Capital Stack Structures in Miami Commercial Deals
Published · Updated · 8 min read
The capital stack defines how a commercial real estate investment is financed—the combination of debt and equity layers that fund an acquisition or development. Understanding capital stack structures is essential for optimizing returns, managing risk, and negotiating deal terms in Miami's competitive commercial real estate investment market. Each layer in the stack carries different risk, return, and priority characteristics.
What Is a Capital Stack in Commercial Real Estate?
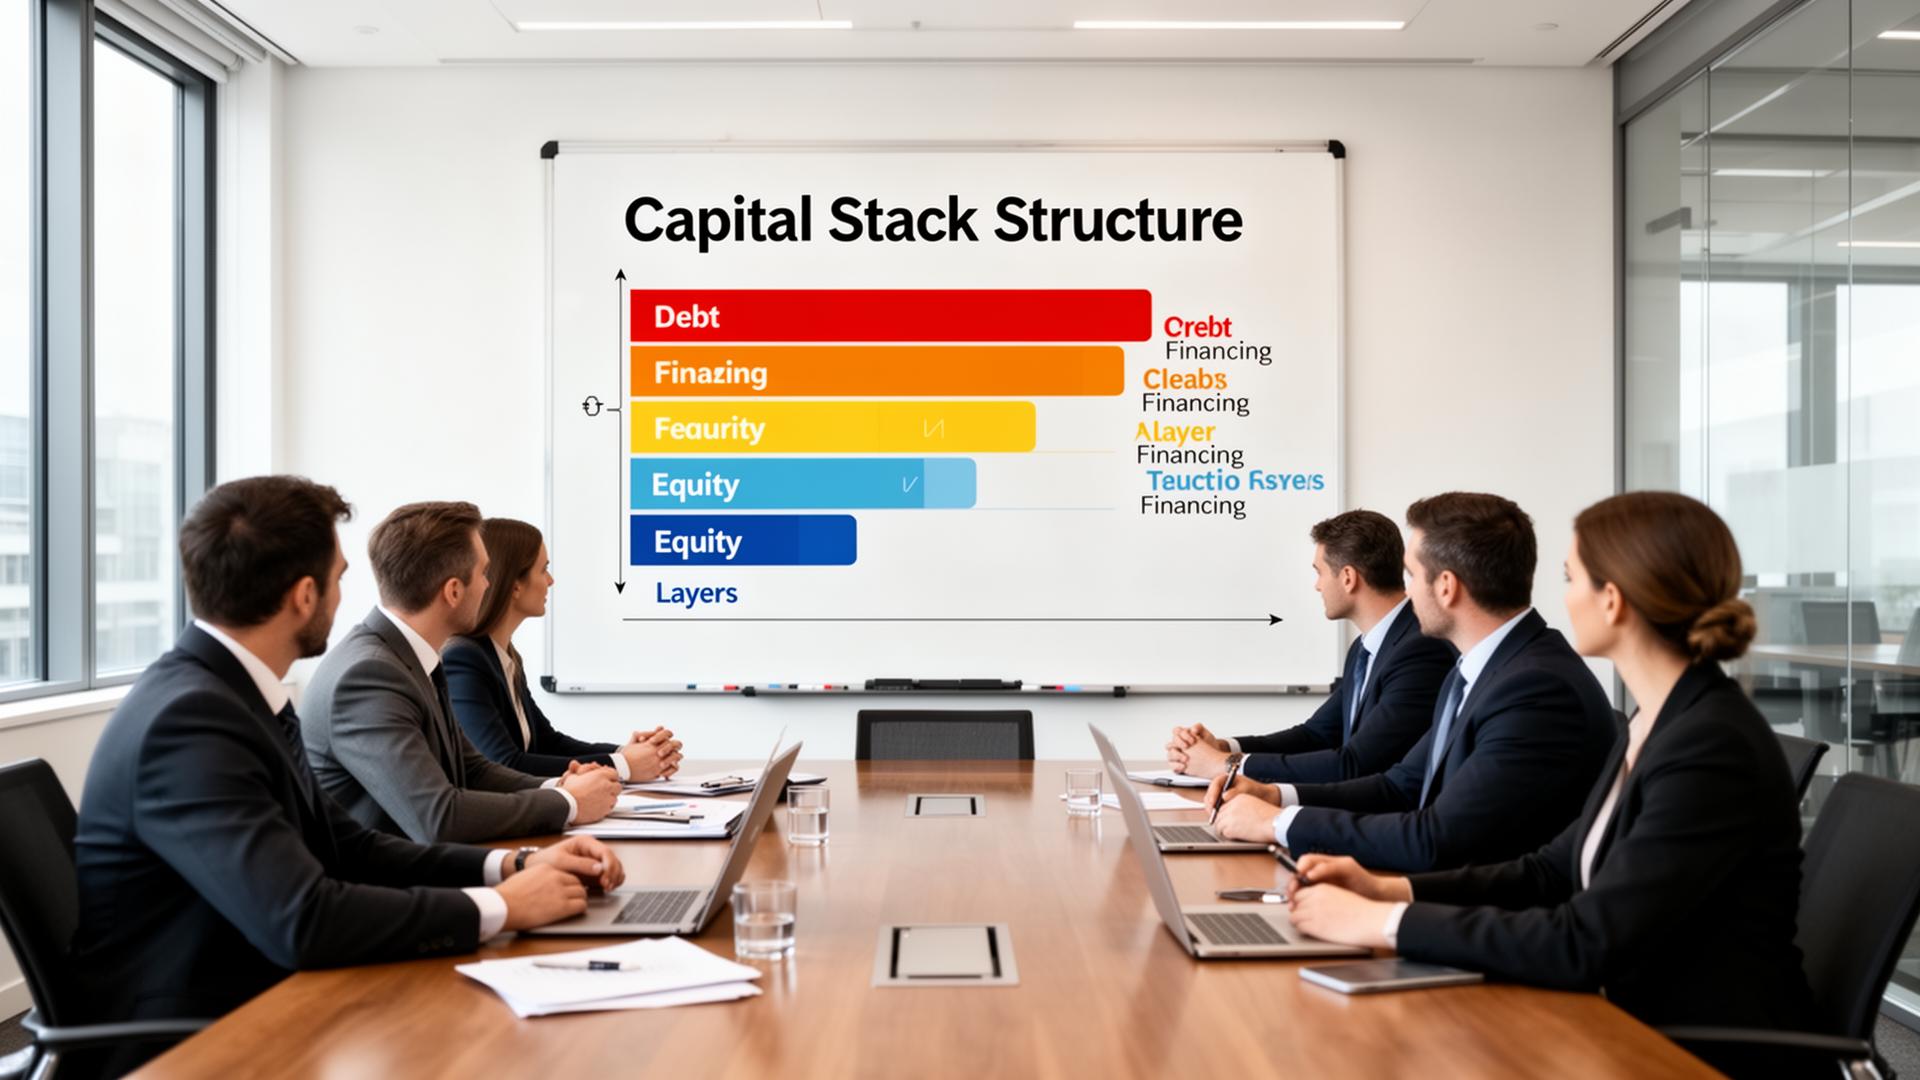
Definition: The capital stack is the complete structure of debt and equity used to finance a commercial real estate acquisition or development. It defines the order of priority for cash flow distributions and liquidation proceeds, with senior debt receiving payment first and common equity last.
The four primary layers of a commercial real estate capital stack:
- Senior Debt (First Mortgage): Lowest risk, lowest return. First priority for repayment. Its share of capitalization depends on lender underwriting and deal structure.
- Mezzanine Debt / Subordinate Debt: Higher risk than senior debt, junior in priority. Returns depend on the terms and risk of the investment. Fills the gap between senior debt and equity.
- Preferred Equity: Equity position with priority return above common equity. Returns depend on the terms and risk of the investment. May include participation in upside.
- Common Equity: Highest risk, highest potential return. Last in priority for distributions but captures all remaining upside.
Understanding how these layers interact is fundamental to evaluating commercial property investment opportunities and structuring deals appropriately.
Senior Debt: The Foundation of the Capital Stack
Senior debt (the first mortgage) forms the base of nearly every commercial real estate capital stack. It carries the lowest risk because it has first priority on both cash flow and property liquidation proceeds.
Key characteristics:
- Loan-to-Value (LTV): Set by the lender based on the borrower, asset and underwriting
- Interest rates: Vary by lender type, property quality, and market conditions
- Amortization: 20–30 years for permanent loans; interest-only for bridge loans
- Common lender types: Banks, life insurance companies, CMBS conduits, agency (Fannie/Freddie for multifamily)
Senior debt sources for Miami commercial properties:
- Agency loans: Financing for multifamily, with terms varying by program and borrower
- CMBS: Non-recourse loans for stabilized commercial properties, leverage, amortization and recourse depend on the lender, borrower and asset — request actual term sheets
- Bank loans: Relationship-based lending, often recourse, competitive rates for established borrowers
- Life company loans: Loans for premium institutional assets, leverage, amortization and recourse depend on the lender, borrower and asset — request actual term sheets
Mezzanine Debt: Bridging the Gap
Definition: Mezzanine debt is subordinate financing that sits between senior debt and equity in the capital stack. It is secured by a pledge of the borrower's ownership interest in the property-owning entity, rather than by a mortgage lien on the property itself.
Key characteristics:
- Position: Junior to senior debt, senior to equity
- Interest rates: Depend on risk, loan terms and lender quotes
- Typical size: Depends on the capital stack, senior lender limits and equity available
- Term: Co-terminous with senior debt or shorter
- Security: Pledge of membership interest, not a property mortgage
When mezzanine debt makes sense:
- Reducing the amount of equity required from sponsors and investors
- Achieving higher leverage without exceeding senior lender's LTV limits
- Value-add acquisitions where additional capital is needed for improvements
- Development projects requiring bridge financing during construction and lease-up
Preferred Equity: Priority Return with Upside Potential
Definition: Preferred equity is an equity investment that has priority over common equity for distributions and liquidation proceeds. Unlike debt, preferred equity does not create a loan obligation—it is an ownership interest with preferential payment terms.
Key characteristics:
- Position: Senior to common equity, junior to all debt
- Preferred return: Negotiated, with payment priority over common equity as specified in the agreement
- Upside participation: May include a share of profits above the preferred return
- Term: Typically aligned with the investment hold period
Preferred equity vs. mezzanine debt:
- Preferred equity is not debt—it doesn't trigger default or foreclosure
- Preferred equity may be more flexible in workout situations
- Senior lenders may prohibit mezzanine debt but allow preferred equity
- Preferred equity investors may have voting rights and governance participation
Common Equity: Risk and Reward at the Top of the Stack
Common equity represents the highest-risk, highest-potential-return position in the capital stack. Common equity investors are the last to receive distributions but capture all remaining upside after other obligations are satisfied.
Common equity structures in Miami commercial deals:
- Sponsor equity: The operating partner's capital contribution (typically 5–20% of total equity)
- LP equity: Limited partner investors providing the majority of equity capital
- Promoted interest (promote): Sponsor receives a disproportionate share of profits above certain return hurdles
Typical promote structure:
- 0–8% return: 90% to LPs, 10% to sponsor
- 8–12% return: 80% to LPs, 20% to sponsor
- 12%+ return: 70% to LPs, 30% to sponsor
This waterfall structure aligns sponsor and investor interests by rewarding the sponsor for generating above-target returns. Understanding cash-on-cash return at each tier is essential.
Capital Stack Examples for Miami Property Types
Capital stack structures vary by property type, risk profile, and market conditions. Here are hypothetical structures for Miami commercial acquisitions:
Stabilized multifamily acquisition ($10M):
- Senior debt (Agency): $7.5M (75% LTV)
- Common equity: $2.5M (25%)
Value-add office acquisition ($15M):
- Senior debt (Bridge): $10.5M (70% LTC)
- Preferred equity: $1.5M (10%)
- Common equity: $3.0M (20%)
Industrial development ($20M total cost):
- Construction loan: $13M (65% LTC)
- Mezzanine debt: $2M (10%)
- Sponsor equity: $1M (5%)
- LP equity: $4M (20%)
Each structure reflects the risk profile, lender requirements, and return expectations appropriate for the investment strategy. The Miami-Dade Economic Resources department provides market data that informs capital structure decisions, while the Florida Office of Financial Regulation oversees lending practices across the state.
Optimizing the Capital Stack for Maximum Returns
Strategic capital stack structuring can significantly impact investor returns. Key optimization principles:
- Evaluate leverage: Compare the cap rate with the loan constant and account for debt service, including amortization, operating expenses, reserves and capital expenditures when assessing returns
- Layer capital efficiently: Fill the gap between senior debt and equity with the lowest-cost subordinate capital available
- Align interests: Structure waterfall and promote terms to incentivize sponsor performance
- Match maturity: Ensure debt terms align with investment hold period to avoid refinancing risk
- Preserve flexibility: Maintain prepayment optionality and avoid restrictive covenants that limit exit timing
For detailed return analysis across different capital structures, refer to our cap rate and underwriting guides.
Capital Stack Advisory from Supreme CRE Miami
Supreme Capital Commercial Real Estate Miami helps investors and developers structure optimal capital stacks for acquisitions and development projects across South Florida.
- Debt and equity sourcing advisory
- Capital structure optimization and modeling
- Lender and equity partner introductions
- Joint venture structuring and negotiation
- Refinancing and recapitalization advisory
Contact our commercial real estate brokers to discuss capital structuring for your next Miami commercial real estate investment.
Related Resources
Frequently Asked Questions
What is a capital stack in commercial real estate?
The capital stack is the complete structure of debt and equity used to finance a commercial property acquisition or development. It defines the priority order for cash flow distributions during operations and the order of capital return upon sale or liquidation—with senior debt receiving payment first and common equity last.
Understanding the capital stack is essential because an investor's position within it determines both their risk exposure and return potential. Senior debt holders accept lower returns in exchange for repayment priority and collateral security, while common equity investors accept the highest risk but capture all remaining upside after other obligations are satisfied.
What are the layers of a capital stack?
The four primary layers are: senior debt (first mortgage) at the base, mezzanine debt between senior debt and equity, preferred equity with priority over common equity, and common equity at the top carrying the highest risk and highest potential return.
Not every deal uses all four layers. Simple acquisitions may use only senior debt and common equity. More complex transactions—particularly value-add and development deals—layer mezzanine debt or preferred equity to reduce the common equity requirement while maintaining acceptable leverage levels and lender covenant compliance.
What is the difference between mezzanine debt and preferred equity?
Mezzanine debt is secured by a pledge of ownership interest in the property-owning entity and creates a loan obligation with foreclosure rights on the membership interest. It functions as debt with fixed payments, default triggers, and intercreditor agreement requirements with the senior lender.
Preferred equity is an ownership position with priority distribution rights but no foreclosure mechanism—it does not create a loan obligation. Preferred equity may offer more flexibility in workout situations and is sometimes permitted by senior lenders who prohibit mezzanine debt. The choice between the two depends on senior lender restrictions, tax considerations, and negotiation dynamics between capital providers.
What is a promote in commercial real estate?
A promote (or promoted interest) is a disproportionate share of profits paid to the deal sponsor or operating partner above certain return hurdles. The promote structure incentivizes the sponsor to maximize investor returns by rewarding outperformance with an increasing share of profits at each return tier.
As an illustrative, negotiated example only (not a market norm), a promote waterfall might distribute 90/10 (LP/sponsor) up to an 8% IRR hurdle, then 80/20 from 8–12%, and 70/30 above 12%. This alignment ensures that the sponsor earns their highest compensation only when investors achieve above-target returns, creating powerful incentive alignment between operators and capital partners.
How much equity is typically required for a commercial acquisition?
Required equity varies by property, transaction and lender, and may include both sponsor and limited partner contributions. Senior debt may cover part of the purchase price, with the remaining gap funded by equity. Mezzanine debt or preferred equity can reduce common equity requirements but may add costs and risks.
Sponsor equity contribution (the operating partner's own capital) varies by deal, with limited partner investors potentially providing the balance. Institutional investors and lenders may require sponsor co-investment to align interests and demonstrate the operator's commitment to the deal.
What is the optimal leverage for commercial real estate?
There is no single optimal leverage level. It depends on the strategy, cash flow, debt terms and risk tolerance. Higher leverage can amplify returns when borrowing costs, including amortization, are below the property's yield, and amplifies losses when they are not.
The optimal leverage level balances return enhancement against risk exposure. Conservative investors may prefer lower leverage to maintain larger equity cushions and lower debt service obligations, while aggressive sponsors may push leverage to 75–80% using mezzanine or preferred equity to maximize equity returns. Lender DSCR requirements often serve as the practical constraint on maximum leverage regardless of investor preference.